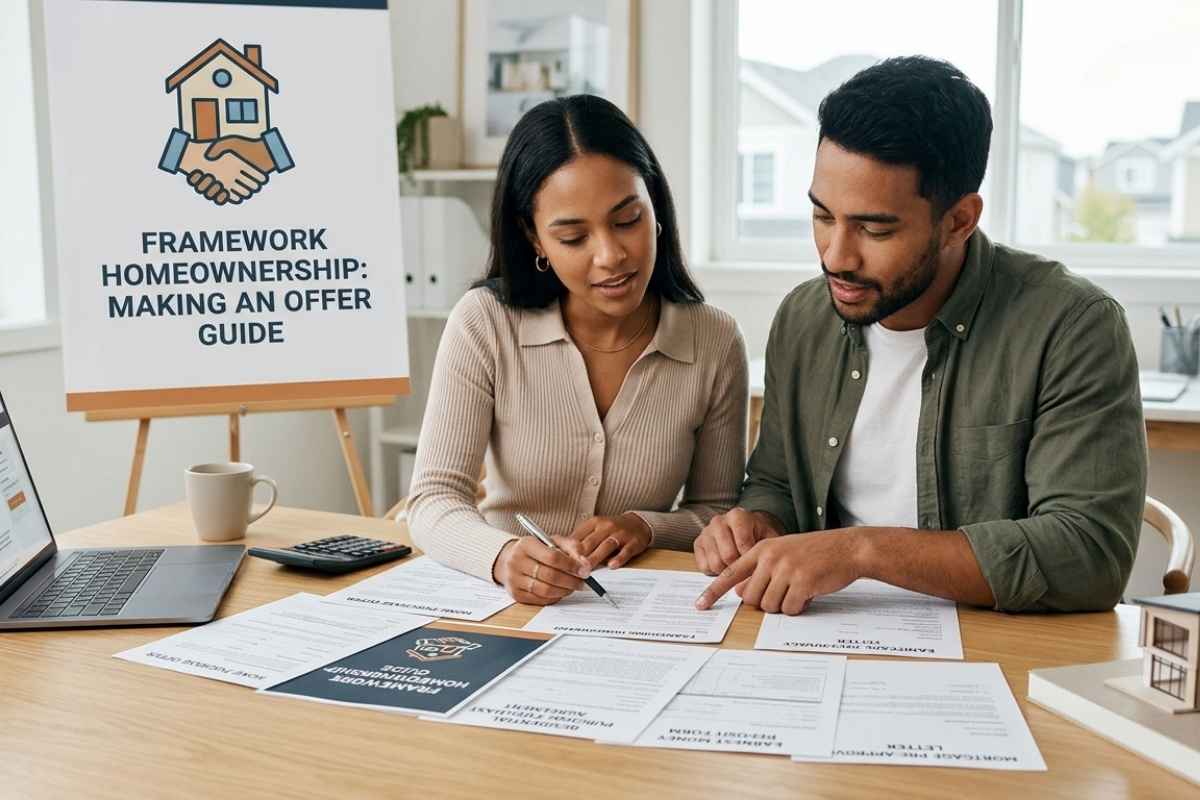
If you have taken the Framework homebuyer education course, you already know it’s built to walk first-time buyers through every stage of the home-buying process in plain language.
One of the most important and most confusing stages for new buyers is making an offer. Search interest around “framework homeownership quiz answers 2020 making an offer” usually comes from people who finished (or are working through) that module and want to double-check what they learned, not just memorize a quiz key.
This guide breaks down what the Making an Offer section of Framework’s course actually covers: how offers work, what goes into a strong one and how sellers typically respond.
Instead of a list of quiz answers, you’ll get the underlying knowledge, so you understand the “why” behind each concept which is far more useful once you’re actually house hunting.
What Is the Framework Homebuyer Course?
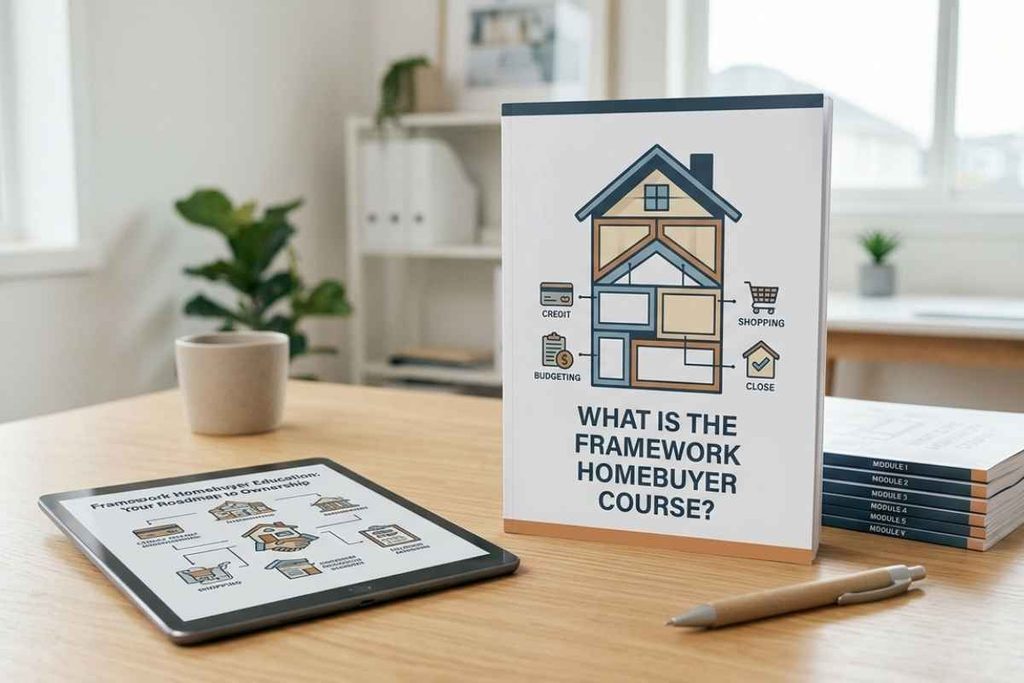
Framework is a nonprofit-backed online homebuyer education platform. Its course is approved for many down payment assistance programs and is one of the courses accepted for Fannie Mae’s HomeReady mortgage program, alongside options like Fannie Mae’s own HomeView course.
The course is broken into modules covering budgeting, credit, shopping for a home, financing, making an offer and closing.
The “Making an Offer” module sits roughly in the middle of the course, right after the shopping-for-a-home section and before financing and closing.
It’s designed to prepare buyers for the moment they’ve found a home they want and need to formally propose to buy it.
Understanding the “Making an Offer” Stage
An offer is a formal, written proposal from a buyer to a seller, stating the price and terms under which the buyer is willing to purchase the home. Once a buyer submits an offer, the process moves from informal house-hunting into a structured, legally binding negotiation.
The Framework course frames this stage around three possible outcomes once an offer reaches the seller:
- Acceptance — the seller agrees to the terms as written and both parties move toward a signed purchase agreement.
- Rejection — the seller declines and the buyer either walks away or submits a new offer later.
- Counteroffer — the seller proposes changes to price, closing date or contingencies and negotiation continues until both sides agree or the deal falls through.
Key Components of a Home Purchase Offer
Every offer, regardless of state or lender, tends to include the same core elements. Framework’s course walks through each of these in detail because getting them right affects both how competitive an offer looks and how protected the buyer is.
Offer Price
The dollar amount the buyer proposes to pay. This is usually based on comparable sales (“comps”) in the area of recently sold homes similar in size, condition and location — rather than just the seller’s asking price. Offering below, at or above asking price depends on how competitive the local market is.
Earnest Money Deposit
A good-faith deposit, typically 1–2% of the purchase price, that the buyer submits along with the offer to show they’re serious. It’s held in escrow and applied toward the down payment or closing costs at closing. If the buyer backs out for a reason not covered by a contingency, they can’t risk losing this deposit.
Contingencies
Conditions that must be met for the sale to move forward, giving the buyer a way to walk away and get their earnest money back if something goes wrong. The most common contingencies covered in the course are:
- Home inspection contingency — lets the buyer back out or renegotiate if a professional inspection reveals major issues.
- Financing/mortgage contingency — protects the buyer if they’re unable to secure final loan approval.
- Appraisal contingency — protects the buyer if the home appraises for less than the offer price.
- Sale contingency — makes the offer conditional on the buyer selling their current home first.
Closing Timeline
The proposed date by which the sale must close and ownership transfers. This needs to work for both the buyer’s financing timeline and the seller’s moving plans and it’s a common point of negotiation.
Steps to Prepare Before You Make an Offer
Framework’s course emphasizes preparation before a buyer ever submits paperwork. The general sequence looks like this:
- Get pre-approved, not just pre-qualified. Pre-qualification is a rough estimate based on self-reported numbers; pre-approval means a lender has actually verified your finances and committed to a specific loan amount. Sellers take pre-approved buyers far more seriously.
- Research comparable sales with your agent so your offer price is grounded in real market data, not guesswork.
- Decide your must-haves versus nice-to-haves, so you know which contingencies matter most to you and where you have room to be flexible.
- Work with your real estate agent to draft the formal purchase agreement, which turns your offer into a legally binding document once signed.
- Set a response deadline. Sellers aren’t required to respond by any set time unless the offer specifies one buyer commonly give a 24 to 72-hour window.
How Sellers Typically Respond to an Offer
Once your agent delivers the offer, expect one of the three outcomes mentioned earlier. Counteroffers are especially common in competitive markets and can go back and forth several times before both sides land on final terms or the deal falls through.
Each counteroffer is essentially a new offer, so the same review process (price, contingencies, timeline) applies each time.
Common Mistakes Buyers Make When Making an Offer

The course highlights several avoidable mistakes that weaken an offer or put buyers at financial risk:
- Skipping mortgage pre-approval. Without it, sellers may not view the offer as serious, especially in a competitive market.
- Ignoring comparable sales. Offering based on the asking price alone, without checking what similar homes actually sold for, risks overpaying.
- Overlooking hidden costs. Closing costs, inspection fees and potential repair costs go beyond just the offer price.
- Rushing the offer. Skipping careful review of contingencies and terms to move fast can create costly problems later.
- Not getting terms in writing. Verbal agreements aren’t enforceable — everything needs to be documented in the purchase agreement.
- Offering the full asking price by default. In many markets there’s room to negotiate and starting too high leaves no flexibility.
Who Else Is Involved When You Make an Offer
Making an offer isn’t something a buyer handles alone. By this stage of the process, a few key professionals are typically already involved:
- Real estate agent — helps prepare, submit and negotiate the offer.
- Loan officer or mortgage broker — provides the pre-approval letter that backs up the offer.
- Real estate attorney — required in some states to review the offer and closing documents.
- Home inspector and appraiser — come into play once an offer is accepted, tied to the inspection and appraisal contingencies.
Documents You’ll Typically Need
When submitting an offer, buyers generally need:
- A valid government-issued ID
- A mortgage pre-approval letter
- The signed offer/purchase agreement itself
How Market Conditions Shape Offer Strategy
The right offer strategy depends heavily on whether you’re in a buyer’s market, a seller’s market or something in between.
- In a seller’s market (more buyers than available homes), expect multiple offers on desirable properties, less room to negotiate on price and shorter response windows. Buyers often need to offer at or above asking price, keep contingencies tighter and move quickly.
- In a buyer’s market (more homes than buyers), sellers are typically more open to negotiation, price reductions and buyer-friendly contingencies, since there’s less competition for their listing.
- In a balanced market, offers tend to land closer to asking price with standard contingencies and negotiations move at a more predictable pace.
Your real estate agent can tell you which type of market you’re in locally, since conditions vary block by block, not just city by city.
Advanced Tips for Competitive Markets
When multiple buyers are bidding on the same home, a few strategies can make an offer stand out without necessarily requiring the highest price:
- Shorten or waive non-essential contingencies where you’re comfortable doing so for example, skipping a sale contingency if you don’t need to sell another home first.
- Include an escalation clause, which automatically increases your offer by a set increment above competing bids, up to a maximum you set.
- Offer a flexible closing date that accommodates the seller’s timeline, which can matter as much as price to some sellers.
- Write a personal letter to the seller, in markets where this is still common and appropriate, explaining why you want the home though some agents now advise against this due to fair housing concerns.
- Stay pre-approved and ready to move fast, since delays in submitting documentation can cost a buyer a competitive property.
Differences in Home Buying Steps by Region
While the core structure of making an offer price, earnest money, contingencies, closing timeline is consistent nationwide, some details vary by state or region:
- Attorney involvement: Some states legally require a real estate attorney to review offers and closing documents, while others rely primarily on agents and title companies.
- Earnest money customs: Typical deposit amounts and how they’re held (directly with the seller’s agent, a title company or an attorney) can differ by region.
- Disclosure requirements: What sellers are legally required to disclose about a property’s condition varies from state to state.
Because of this, it’s worth confirming local practices with your agent or a local housing counselor rather than assuming national norms apply exactly where you’re buying.
Why This Matters Beyond the Course
Understanding the making-an-offer process isn’t just about finishing a course module it directly affects how buyers negotiate in the real world.
Buyers who understand offer price strategy, contingencies and earnest money tend to make more competitive, better-protected offers and they’re less likely to be caught off guard by a counteroffer or a rejected bid.
Final Thoughts
The “Making an Offer” module in Framework’s homebuyer course exists to prepare you for a real, high-stakes moment in the home-buying process, not just to test recall.
Understanding offer price strategy, earnest money, contingencies and how sellers respond will serve you far better when you’re actually negotiating for a home than memorizing a set of quiz answers ever could.
FAQ’s
Does Fannie Mae accept Framework homebuyer education?
Framework’s course is accepted for several mortgage and down payment assistance programs, including options tied to Fannie Mae’s HomeReady program. Fannie Mae also offers its own course, HomeView, as an alternative.
Is the Framework homebuyer course free?
Framework’s course typically has a nominal fee, though it’s often covered or reimbursed through partner lenders, employers or down payment assistance programs check with your local housing counseling agency.
What’s the difference between pre-qualification and pre-approval?
Pre-qualification is a rough, self-reported estimate of what you might be able to borrow. Pre-approval involves a lender verifying your financial documents and issuing a conditional commitment for a specific loan amount, which carries far more weight with sellers.
How much earnest money should I offer?
It varies by market, but 1–2% of the purchase price is typical. In highly competitive markets, buyers sometimes offer more to strengthen their bid.
Can a seller accept multiple offers at once?
No, a seller can only formally accept one offer. However, they can field multiple offers simultaneously and choose which one to accept, reject or counter.
What happens if my offer is rejected?
You can typically submit a revised offer, either right away or later if the property remains on the market or moves on to another home.
Do I need a real estate attorney to make an offer?
It depends on your state. Some states, including New York and Massachusetts, legally require an attorney to review the offer and closing documents. In others, agents and title companies handle most of the paperwork and an attorney is optional but still useful for extra protection.